How to Handle Shared Debts and Divorce Assets
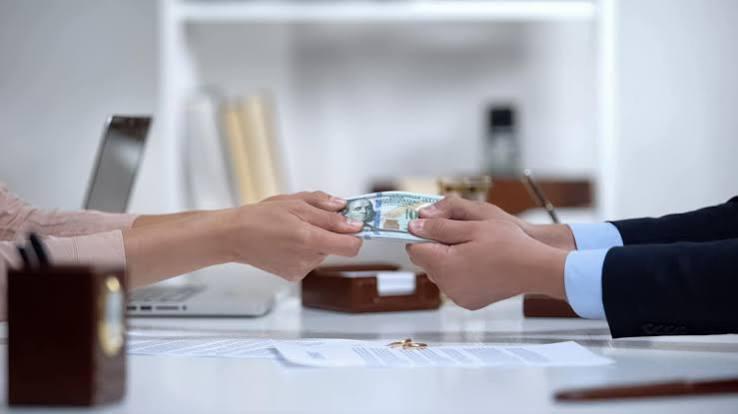
Divorce can create financial challenges, especially when couples need to divide their property, savings, investments, and outstanding debts. While many people focus on who will receive the family home or other valuable belongings, managing shared financial responsibilities is equally important. Understanding how to handle Divorce Assets and shared debts can help both parties avoid unnecessary disputes and make informed decisions about their financial future. From mortgage payments and credit cards to personal loans and jointly owned property, every financial responsibility should be carefully reviewed before reaching a final settlement. With proper documentation, accurate financial information, and professional legal guidance, individuals can work towards a fair and manageable financial arrangement.
What Are Shared Debts and Divorce Assets?
Shared debts are financial obligations that both spouses may be legally responsible for, depending on the loan agreement and applicable laws. These debts can include joint mortgages, credit cards, personal loans, car finance, and other borrowing arrangements.
Divorce Assets refer to valuable resources that may need to be considered during financial settlement proceedings. These can include:
Family homes and other properties.
Joint bank accounts and savings.
Vehicles and valuable personal belongings.
Business interests and investments.
Pensions and retirement savings.
Understanding the difference between assets and liabilities is essential. Assets represent financial value, while debts reduce the overall financial position. Reviewing both provides a clearer picture of the couple's financial circumstances.
Why Is It Important to Manage Shared Debts During Divorce?
Managing shared debts properly can prevent financial difficulties after separation. If financial responsibilities are not clearly addressed, one spouse may continue facing problems with payments or outstanding balances.
There are several reasons why careful debt management matters.
1. Prevents Financial Disagreements
When both parties understand their outstanding debts, it becomes easier to discuss payment responsibilities. Clear financial records reduce misunderstandings and support more productive negotiations.
2. Protects Financial Stability
Unpaid loans and credit card balances can affect future financial planning. Reviewing these obligations helps individuals understand their financial commitments and prepare realistic budgets.
3. Reduces Legal Complications
Unresolved financial responsibilities may create further disputes during or after divorce proceedings. Addressing debts early can help both parties understand their obligations under the relevant legal arrangements.
4. Supports Fair Financial Settlements
Considering both assets and liabilities helps create a more complete picture of the available financial resources. This makes it easier to discuss settlement options based on accurate information.
How to Identify Shared Debts and Divorce Assets
Before discussing a financial settlement, both parties should prepare a complete record of their financial resources and obligations.
Collect Bank and Loan Statements
Start by gathering recent bank statements, credit card bills, mortgage documents, and loan agreements. These records help establish outstanding balances, payment schedules, and account ownership.
List All Valuable Assets
Prepare a detailed list of properties, vehicles, investments, savings, and other valuable belongings. Include assets owned jointly and relevant individual assets.
Review Ownership and Financial Responsibility
Check whose name appears on each account, loan, or ownership document. Legal responsibility does not always depend on who originally used the money or purchased an item.
Identify Outstanding Payments
Record monthly mortgage instalments, loan repayments, credit card balances, and other financial commitments. This information helps both parties understand their ongoing responsibilities.
How to Divide Shared Debts During Divorce
Dividing shared debts requires careful consideration of ownership, loan agreements, financial circumstances, and local family laws.
Joint Mortgages
A family home may have significant financial value but also carry an outstanding mortgage. Couples may consider selling the property and using the proceeds to repay the mortgage before distributing any remaining equity.
Another option may involve one spouse keeping the property and refinancing the mortgage, subject to lender approval. A divorce agreement alone does not automatically remove the other spouse from a joint mortgage.
Credit Card Debts
Joint credit card accounts should be reviewed carefully to establish outstanding balances and payment responsibilities. Both parties should identify which purchases created the debt and discuss an appropriate financial arrangement.
However, if both individuals are legally responsible under the credit agreement, an arrangement between spouses may not automatically change the lender's rights.
Personal Loans
Personal loans should be examined to determine who borrowed the money, who signed the agreement, and how the funds were used. Depending on the applicable law, the circumstances may influence how the debt is considered during divorce proceedings.
Vehicle Finance
Cars purchased through finance agreements may involve outstanding payments and ownership restrictions. Couples should review the agreement and consider whether selling the vehicle, transferring it with lender approval, or continuing payments is appropriate.
How Divorce Assets Affect Shared Debt Settlements
The value of Divorce Assets can influence discussions about how outstanding debts should be managed. A fair financial assessment should consider both valuable possessions and financial liabilities.
For example, a couple may own a property worth £200,000 with an outstanding mortgage of £80,000. The available equity would be £120,000 before considering other costs or legal adjustments.
If the property is sold, the mortgage would normally need to be repaid from the proceeds. The remaining amount can then be considered as part of the wider financial settlement.
Similarly, one spouse may receive a larger share of savings while agreeing to take responsibility for certain financial obligations. Whether such an arrangement is legally appropriate depends on the circumstances and applicable law.
Common Mistakes to Avoid When Managing Shared Debts
Financial mistakes during divorce can create unnecessary complications and long-term difficulties. Both parties should avoid the following:
Ignoring outstanding debts: Focusing only on property and savings can result in an incomplete financial assessment.
Missing payment deadlines: Unpaid joint debts may affect credit records and create additional charges.
Assuming responsibility automatically changes: A divorce agreement does not necessarily remove someone from a joint loan or credit agreement.
Hiding financial information: Failing to disclose relevant assets or liabilities can create serious legal consequences.
Signing agreements without advice: Financial settlements should be reviewed carefully before becoming final.
Avoiding these mistakes can help individuals manage their finances more responsibly during separation.
How to Protect Your Financial Interests During Divorce
Protecting your financial position requires careful preparation and an understanding of your legal responsibilities.
Consider these practical steps:
Maintain copies of all financial documents and loan agreements.
Review joint bank accounts and credit arrangements.
Monitor payments on outstanding debts.
Obtain independent valuations of significant assets.
Discuss refinancing or transferring loans with the relevant lenders.
Seek professional legal and financial advice before signing a settlement.
Taking these steps can help reduce financial uncertainty and protect your interests throughout the divorce process.
Why Professional Legal Advice Matters
Family lawyers can explain how shared debts and Divorce Assets may be treated under the applicable legal system. They can also help review financial disclosure, negotiate settlement terms, and identify potential risks involving joint loans or property ownership.
Financial advisers and accountants may provide additional support when dealing with complicated investments, business interests, and significant liabilities.
Professional guidance is particularly important when one spouse has limited access to financial information or when disagreements arise over debt responsibility.
Conclusion
Handling shared debts and Divorce Assets requires careful planning, accurate financial information, and a clear understanding of legal responsibilities. Couples should identify all valuable possessions, review outstanding liabilities, and understand their obligations under existing loan agreements. Addressing mortgages, credit cards, personal loans, and other financial commitments early can reduce disputes and support a more manageable settlement. With professional legal advice and proper financial documentation, both parties can make informed decisions and work towards greater financial stability after divorce.
Join the Conversation
Share Your Thoughts
Related Articles
What Are the Benefits of University of Wolverhampton?
Explore the courses offered by the University of Wolverhampton, including undergraduate and postgraduate programs, popular subjects, and study options for international students.
University of Wolverhampton Entry Requirements Guide
University of Wolverhampton foundation year: entry requirements, IELTS 5.5, and fees from £17,600, plus free guidance on your eligibility.

What Are the Key Rules of Contract Law
Contract lawyer in Lahore for drafting, reviewing, and amending contracts, and resolving contract disputes. Book a consultation with Rana & Baig Law Firm.